 We respect your privacy. Please refer to our full
Project Finance Jobs: How to Launch Yourself into an Orbital Data Center with an SPV and Sculpted Debt
We’ve previously covered Project Finance jobs across several articles, but the comprehensive feature was quite old, so it seemed like a good time for a refresh.
Plus, we now have a full Project Finance course and many case studies submitted by students over the years, so the descriptions of careers and interviews should be more accurate.
Before jumping into the deep end of the Excel pool, I’ll start in the shallow waters with the key definitions and firm types:
- What Are “Project Finance Jobs?”
- Project Finance vs. Leveraged Finance vs. Investment Banking vs. Infrastructure Private Equity
- How Project Finance Deals Work
- Project Finance Modeling and Deal Work
- Project Finance Careers, Compensation, and Lifestyle
- The Top Project Finance Firms and Banks
- Project Finance Recruiting and Interviews
- Project Finance Interview Questions
- Exit Opportunities
- Are Project Finance Jobs for You?
What Are “Project Finance Jobs?”
The Project Finance vs. Corporate Finance article presents the basic definition:
Project Finance Definition: “Project Finance” refers to acquisitions, debt/equity financings, and new developments of capital-intensive infrastructure assets that provide essential utilities and services.
So, Project Finance includes sectors like utilities, transportation, social infrastructure, energy, and natural resources, and it focuses on assets that last for decades, have stable/predictable cash flows, use substantial Debt, and often size and sculpt Debt to match the future cash flows.
“Project Finance” at banks refers to the lending side of the industry (debt financings), but people often use it more broadly to refer to equity and M&A deals involving these assets.
In terms of firm types, there are investment and commercial banks that advise on these deals, developers and power/utility firms that acquire and build new assets, and consulting firms that work on the engineering, insurance, and operational aspects.
Within these categories, firms use different strategies.
For example, some developers build assets to sell to utility/power companies, while others, such as independent power producers (IPPs), develop and hold projects for the long term.
Buy-side firms, such as infrastructure private equity firms, are in a different category, but you could potentially add them to this list as well.
Project Finance vs. Leveraged Finance vs. Investment Banking vs. Infrastructure Private Equity
There is overlap between these fields, but also some key differences:
- Investment Banking: Both IB and PF “work on deals,” but investment banking is a much broader industry that works on more than just infrastructure assets and debt deals; it includes other product groups and many industry groups.
- Leveraged Finance: LevFin is similar in that it’s the group within IB that sets up financing for deals and syndicates it to other lenders, but it focuses on corporate-level deals across varied industries rather than asset-level deals in infrastructure.
- Infrastructure Private Equity: This is the “equity investing” side of infrastructure. Roughly speaking, Infrastructure Investing : Project Finance :: Private Equity : Large Bank Lenders. But there is now an overlap because many large PE firms have gotten into private credit, and these groups often fund infrastructure assets, such as data centers.
We sometimes get questions about Public Finance and Debt Capital Markets (DCM) and how they compare.
Although these fields both deal with debt, they are quite far removed from Project Finance (in my view), so I would not even put them in the same category.
Public Finance advises on debt issuances for governments, publicly owned companies, and non-profits. Some of these issuances fund infrastructure assets, but the deal process, clients, fees, and modeling process are all quite different (see the article for details).
Debt Capital Markets focuses on debt funding for “general corporate purposes” rather than deals, and there’s little technical work or granular modeling. And, like LevFin, it focuses on corporate deals rather than asset-level ones.
How Project Finance Deals Work
As in all debt-related groups, you focus heavily on the downside risk when deciding on the deals to fund and the terms to offer.
To illustrate, let’s say that you’re working on a Debt issuance to fund a developer’s new offshore wind farm.
Step 1 is that this developer (or other equity investor) sends your group an “information pack” or Confidential Information Memorandum (CIM) with details on the asset’s financials, the business plan, and the overall market.
This CIM might have a suggestion for the amount and type of Debt they want to use, but this varies heavily based on the investors and their relationship with you.
But just for fun, let’s say that this offshore wind farm has contracted pricing and volumes via a Power Purchase Agreement (PPA), so the revenue over 10 or 20 years is known in advance.
Since the equity investors believe it’s fairly low risk, they initially “expect” something like 80% Debt for the construction funding and £1.2 billion of Permanent Loans to replace the Construction Loan when the new development finishes, which is based on a targeted Debt Service Coverage Ratio (DSCR) of 1.50x.
In Step 2, you go into “evaluation mode,” decide whether you want to do the deal at all, and if you do, make your own proposal for the terms.
You consider everything from your relationship with the sponsor and their track record to the deal structure and your own version of the model.
To set this up, you consider everything that might go wrong:
- What if the PPA agreement falls through or expires, and the asset must revert to market demand and prices?
- What if there’s a construction delay or a budget overrun?
- What if there’s significant operational downtime for repairs and maintenance?
- What if the wind turbines end up producing less energy than expected, such as in the “P75” and “P90” cases?
The list goes on, but here are example scenarios you might construct:
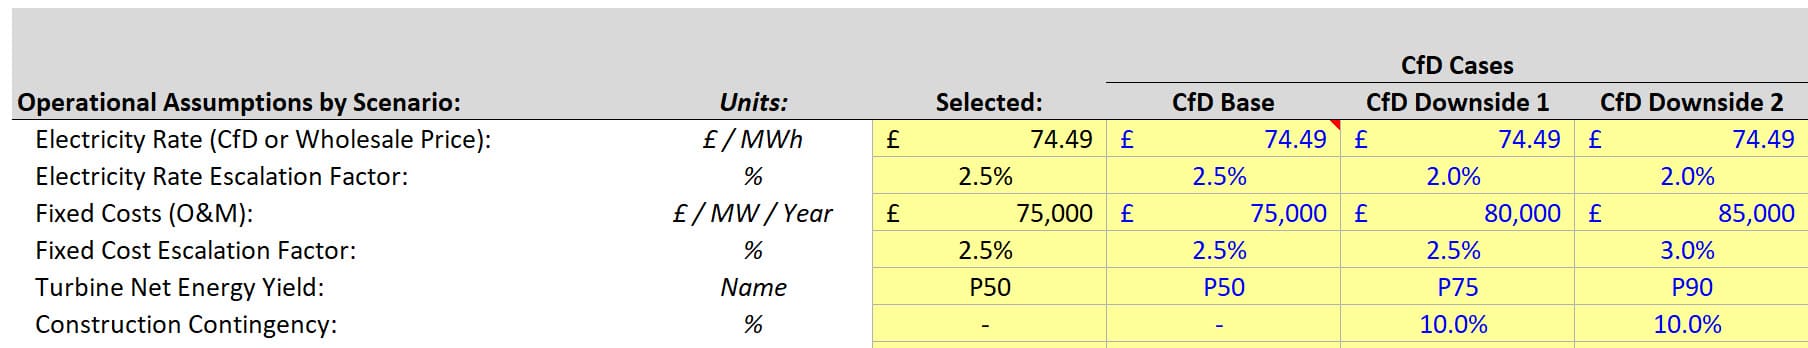
You’ll evaluate the credit stats and ratios, such as the DSCR, in different cases, and look at the potential recoveries in the case of a true disaster, such as the asset shutting down.
For example, if that happens, how much could you sell the remaining assets for, and would the proceeds cover the remaining Debt? How does the Special Purpose Vehicle (SPV) affect things (i.e., does it reallocate some assets to other entities and make them “off-limits” to you?).
In this case, maybe the DSCR is “OK-ish” in the Base case, but falls to dangerously low levels in the Downside cases:
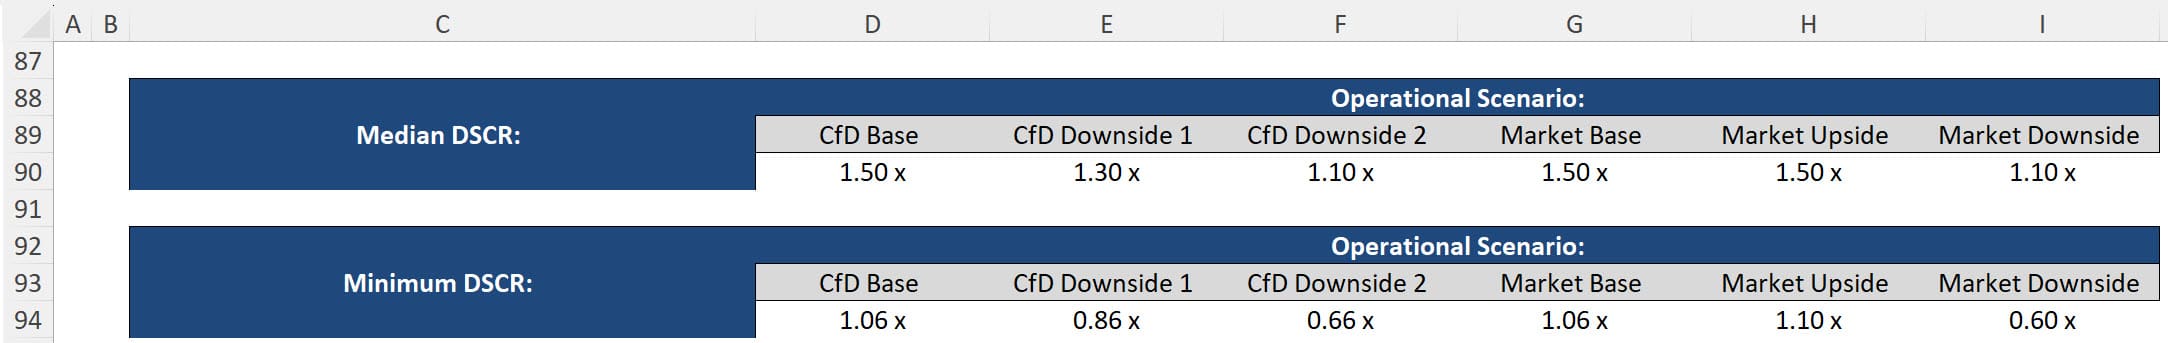
Levels below 1.00x mean the wind farm doesn’t have enough Cash Flow Available for Debt Service to pay for the Interest Expense and scheduled Debt Principal Repayments.
This means it will have to draw on additional Equity (or raise other outside financing), which is negative for everyone involved.
In Step 3, you’ll take these findings and use them to make your own proposal.
For example, maybe the sponsor wanted Debt with a 7% interest rate, 15-year maturity, and 1.50x minimum DSCR, but your team is only comfortable with a 2.00x minimum DSCR and an 8% interest rate, which implies a much lower level of Debt.
You might end up with a compromise somewhere in the middle, but it depends heavily on the sponsor and the current market.
In Step 4, you’ll recruit other lenders to participate in your syndicate and win approval from each one.
Some of these lenders might want to negotiate the terms further, leading to more back-and-forth among all these groups.
Assuming everyone agrees to something, in Step 5, you’ll return to the developer or equity investors, draft the loan documents, win final approval, and launch the deal.
Project Finance Modeling and Deal Work
Project Finance models are known for being very granular, with assumptions that go down to the level of individual contracts.
The technical work is often more detailed than what standard IB industry or M&A teams do, but it doesn’t necessarily apply to all assets.
For example, there are no “contracts” for many transportation assets, such as toll roads, so the modeling tends to be higher-level and linked more closely to macro drivers, such as population or GDP growth.
Overall, as a junior Analyst or Associate in this group, you can expect to split your time between modeling/technical work, coordination and due diligence, and market and policy research.
There isn’t much “sourcing” because you work on inbound requests and deals, which also means there are fewer “random tasks” than in other IB groups.
Project Finance Careers, Compensation, and Lifestyle
Similar to other credit groups, such as DCM, the hours are often much better in Project Finance.
“Much better” translates into 50 – 60 hours per week for junior employees vs. more like 70 – 80 per week in many traditional IB roles.
In addition to the focus on deals and responses to inbound financing requests, there’s also less of a cultural expectation around “face time” (i.e., sitting in the office late to look busy).
The hours can spike up when you’re on a live deal that gets busy, but they’re still mild next to IB/PE (with much less weekend work).
The hierarchy / career path is the same: Analyst, Associate, VP, Director/SVP, and MD, and you still move into “Project Manager” and then “Sales/Relationship” roles as you move up.
The progression up the ladder is slower but also more “stable”; it might take an extra year or two to reach each level, but you’re less likely to be fired if deal activity falls.
The main downside is that compensation is lower, usually representing a 10 – 30% discount to standard IB pay, depending on the year, group, and region.
Here’s a rough estimate of compensation for U.S.-based Project Finance roles at banks vs. standard IB salaries plus bonuses as of 2026:
- Analyst: $140K – $180K Total (vs. $165K – $225K in IB).
- Associate: $250K – $350K Total (vs. $285K – $500K in IB).
- VP: $450K – $650K Total (vs. $525K – $800K in IB).
- Director: $500K – $750K Total (vs. $700K – $900K in IB).
- Managing Director: $800K – $1.2M Total (vs. $1M – $2M in IB).
If you’re at a developer, such as a utility-scale firm that builds and acquires these assets, it’s sometimes more stressful/intense than at a bank because these deals are your entire business.
Also, unfortunately, compensation is lower, so there’s no “offset” for the longer hours and stress:
- Analyst: $90K – $150K Total.
- Associate / Manager / Senior Associate: $150K – $200K Total.
- Director: $200K – $325K Total.
- VP: $325K – $450K Total.
The hierarchy at developers and utility firms differs from the one at banks, which explains the ordering here.
The Top Project Finance Firms and Banks
The stereotype is that Project Finance deals are dominated by Japanese and French banks, and that’s still mostly true today – though I would add a few other European banks to the list.
Some U.S. banks with large Balance Sheets, such as JPM, Citi, and Wells, are also competitive, and MS works on quite a few “advisory” assignments outside of pure lending deals.
You’ll also occasionally see Canadian banks, such as BMO, CIBC, and RBC, on the list.
But if you look at Project Finance league tables, here are the “usual suspects” of European and Asian banks:
Depending on the year and region, you could add some names to this list (e.g., NordLB, Rabobank, HSBC, and Nomura).
On the developer/utility side, some U.S.-based firms that focus on renewables and digital infrastructure include:
And yes, there are dozens outside the U.S. and many others that focus on fossil fuels, gas, and water infrastructure; for more, see the power & utilities IB article.
Project Finance Recruiting and Interviews
At the large banks, recruiting follows the standard IB timeline, candidate pool, and process (go to a target school, get internships, and network and prepare for interviews far in advance).
You can also get in as a lateral hire from product groups like Leveraged Finance or industry groups with strong overlap, such as Power & Utilities, Renewables, or Infrastructure.
Some candidates also break in from Big 4 firms or business valuation firms specializing in these industries.
If you are a more experienced candidate, you should expect a modeling test or case study.
This will usually take the form of cash-flow projections with Debt service, some Debt sizing and sculpting, and a returns calculation and investment recommendation for equity or debt.
Solar and wind assets seem to be the most common subjects for case studies, but data centers, toll roads, and airports are also possible.
Our Project Finance & Infrastructure course includes case studies based on most of these asset types, including 2 solar examples, an offshore wind farm, a toll road, an airport, a nuclear plant, and a lithium mine:

Project Finance & Infrastructure Modeling
Learn cash flow modeling for energy and transportation assets (toll roads, solar, wind, and gas), debt sculpting, and debt and equity analysis.
learn moreProject Finance Interview Questions
You could easily get standard interview questions about accounting, corporate valuation, and M&A and LBO models, but you are also likely to get some that are specific to Project Finance or Infrastructure.
Here are a few examples:
Q: Why Project Finance?
A: You like working on deals involving long-term assets that provide essential services and do some social good.
You also prefer working on deals rather than operations or sourcing, and you like reviewing many assets, with a focus on downside risk. You find this more interesting than the presentation of the client’s “story” in many other IB groups.
Also, Event X or Person Y from your background is connected to infrastructure, so you heard about the sector from them and became interested like that.
Q: Tell me about a recent infrastructure or Project Finance deal that interests you.
A: We have a tutorial on how to walk through a deal, so you should refer to that.
For debt deals, you should focus on the loan terms, such as the tenor, interest rates, and DSCR/LLCR, rather than the “price paid.”
If you cannot find any asset-level deals, look for corporate-level power, utilities, or renewable deals.
Some good sources for finding them include the Financial Times, InfraPPP, and Infrastructure Investor.
Q: How does a Project Finance (PF) model differ from a leveraged buyout model?
A: PF models are for infrastructure assets rather than entire companies, they cover much longer time frames (decades), they use more leverage (often 50 – 60% Debt), they sculpt and size the Debt to match the future cash flows, and they focus on the cash flows rather than the traditional 3 financial statements.
The “Exit Value” or “Terminal Value” may not exist because many infrastructure assets have fixed useful lives and cannot operate indefinitely into the future.
Finally, PF models include both newly developed assets (greenfield) and existing ones (brownfield), while traditional LBO models are only for existing, operational companies.
Q: Why is it common to size and sculpt Debt based on the future cash flows in Project Finance?
A: It’s because most assets have predictable cash flows due to contracts such as power purchase agreements (PPAs) that lock in prices and even volumes in some cases.
Also, linking the Debt size, interest, and principal repayments to the future cash flows reduces the risk for lenders and aligns the interests of all parties: There’s more repayment when the cash flows are stronger and less when they’re weaker.
Equity investors also favor this approach because it often allows them to use more Debt to fund their deals, which increases their returns if the deals perform well.
They can use more Debt because this approach gives the asset “credit” for its future cash-flow growth.
Q: Wait a second. Earlier, you said that Project Finance models have no Terminal Value or Exit Value, but the targeted Equity IRR is often in the 10 – 15% range. How is this possible?
A: First off, note that the targeted Equity IRR range is often more like 7 – 10% for highly regulated assets, such as a solar plant governed 100% by a PPA from a large utility company.
Higher IRRs are more common when there’s merchant pricing, i.e., the asset sells electricity, transportation, or resources at current market prices.
Having said that, the math “works” because deals use significant leverage, and EBITDA margins and cash-flow yields tend to be high.
For example, many assets produce an average “Cash Flow to Equity” Yield of nearly 10%, depending on the time frame and deal terms:
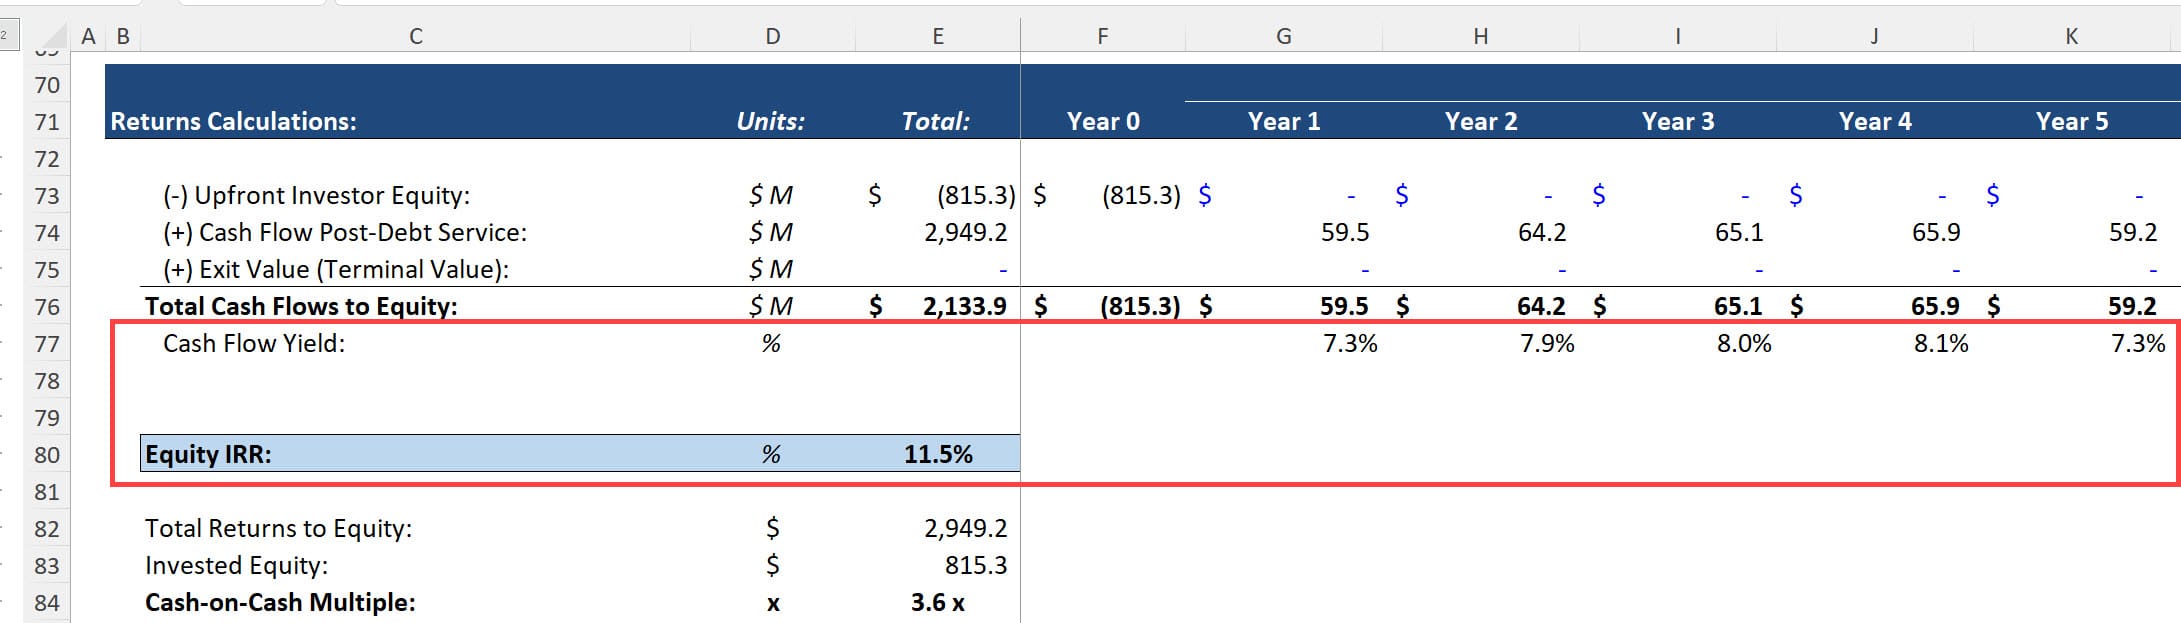
Given these high yields and the high Debt used to reduce the upfront Equity, assets do not need Terminal Values to produce acceptable IRRs.
Q: How do you calculate the Debt Service Coverage Ratio (DSCR) and Loan Life Coverage Ratio (LLCR), and how do you use them in models?
A: We have full tutorials on both, which you should review for more.
But in short: The DSCR equals the Cash Flow Available for Debt Service / (Interest Expense + Scheduled Principal Repayments + Other Loan Fees), and it represents how easily the asset’s cash flows can pay for the required Debt Service in each period.
CFADS definitions vary, but it normally equals EBITDA – Cash Taxes – Maintenance CapEx +/- Change in Working Capital +/- Reserve Contributions and Withdrawals.
The LLCR is defined as the Present Value of the CFADS Over the Loan’s Remaining Tenor divided by the current Debt balance.
In PF models, you use the DSCR and LLCR to size Debt balances and stress-test models.
Q: Imagine that you are a Project Finance lender, and the equity investors send you a business plan that you believe is unrealistically optimistic. How would you modify the model to “stress test” their business case?
A: It depends on the asset, but there’s a good set of starting ideas in the previous section:
- Revenue/Pricing: What if the merchant prices are lower than expected, or the PPA falls through or expires? What if the volumes delivered are below expectations?
- Construction Budget Overruns and Delays: Most assets end up costing more than expected and taking longer to deliver, both of which negatively impact the returns (more upfront funding and development time reduce the IRR).
- Operational Problems: There might be downtime, a loss in energy/resource production, or higher-than-expected operational expenses.
- Financing: What if the Debt used is higher/lower than expected (each one hurts different investors)? What if the interest rates are floating, and they rise to a higher level after macro events?
Exit Opportunities
Project Finance exit opportunities include infrastructure private equity funds, corporate development teams at infrastructure/energy companies, other lending roles (private credit, direct lending, Leveraged Finance, etc.), and related industry groups in IB.
You will not be the strongest candidate for generalist PE roles, hedge fund jobs, or venture capital roles because the skill set and analytical work are too different.
If you want to pursue one of these, you should first move into a traditional IB industry group.
Also, if you want broader exits, working in an advisory role within “Project Finance” tends to be better than a pure lending one.
Finally, working at a large bank tends to be better for exits than working at a developer or consulting firm.
This is mostly because the large banks tend to be in dialogue with infrastructure investors more frequently, and they have more of a “candidate pipeline” to direct to these firms.
Are Project Finance Jobs for You?
Project Finance jobs might be for you if:
- You want to work on a lot of deals, with a focus on assessing the downside risk by poking holes in the equity investors’ optimistic cases.
- You like infrastructure, energy, and renewables, and you’re more interested in “the numbers” than in sourcing deals or working on operations or on-the-ground details.
- You want a better work/life balance than in IB, and you’re willing to accept lower pay.
- You’re interested in a long-term, stable career in a sector that will be around for decades rather than a “flash in the pan” job.
I don’t necessarily think it’s “easier” to break into Project Finance, so this one is not on my list.
If you understand and accept all this, it might just be time to launch your own Special Purpose Vehicle in an orbital data center sent toward Mars.
About the Author
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
Free Exclusive Report: 57-page guide with the action plan you need to break into investment banking - how to tell your story, network, craft a winning resume, and dominate your interviews