 We respect your privacy. Please refer to our full
Private Equity Salary, Bonus, and Carried Interest Levels: The Full Guide
- The TL;DR Version of Private Equity Salaries and Compensation
- What is Private Equity? What Do All These Terms Mean?
- Components of Private Equity Compensation
- What is Carry in Private Equity?
- How Does Carry Work in Private Equity?
- Carried Interest in Middling and Poor Outcomes
- So, What’s the Problem with Carry?
- Will Sky-High Private Equity Salaries, Bonuses, and Carry Last Forever?
We’ve covered private equity salaries and total compensation before, but the old article was desperately in need of an update.
Also, some of the explanations and examples were a bit “off” and deserved more precise treatment.
I’ll start with the cold, hard numbers as of mid-2026 and then explain the nuances:
| Position Title | Typical Age Range | Base Salary + Bonus (USD) | Potential Carry (% of Cash Comp.) | Promotion Time |
|---|---|---|---|---|
| Analyst | 22-25 | $125K-$175K | 0% | 2-3 years |
| Associate | 24-28 | $175K-$400K | 0-5% | 2-3 years |
| Senior Associate | 26-32 | $300K-$550K | 0-10% | 2-3 years |
| Vice President (VP) | 30-35 | $400K-$650K | 10-30% | 3-4 years |
| Director or Principal | 33-39 | $500K-$900K | 30-80% | 3-4 years |
| Managing Director (MD) or Partner | 36+ | $800K-$2M | 100-200% | N/A |
| Managing Partner (MP) | 40+ | $1M-$3M | 200-400% | N/A |
Data Sources: Compensation reports from Heidrick, Selby Jennings, and Charles Aris; various online discussions and threads.
The TL;DR Version of Private Equity Salaries and Compensation
This article will have a lot of numbers, facts, and figures, so here’s an upfront summary:
- The numbers above attempt to capture a wide range of firms, from smaller/startup PE firms to KKR and Blackstone; you will earn more at the PE mega-funds and more in “Tier 1” U.S. cities, like NY, SF, and LA.
- In other regions, expect anything from modest discounts (10 – 20%) to huge haircuts (70%+), depending on whether it’s a developed or emerging market, the firm/fund size, strategy, etc.
- Beyond pure “size,” compensation also has a lot to do with repeated fundraising and the ability of your firm to raise new, larger funds every few years because the management fees on a single fund decline over time.
- You start out earning in the low-six-figure range (e.g., $200K – $350K as an Associate) and advance to $1 million+ in base salary + bonus as you become more senior.
- If you consider just the base salary + bonus, private equity through the mid-levels does not necessarily pay more than investment banking in the current environment (very firm/size-dependent).
- The real upside comes from Carried Interest, which is based on a percentage of PE funds’ investment profits, but it’s modest until you reach the senior levels.
- You should not “bank on” Carried Interest because it’s potential compensation if you stay at your firm for a long time and your funds perform decently well – but PE performance has been declining.
What is Private Equity? What Do All These Terms Mean?
I’m not going to re-explain the private equity industry, so please see our dedicated coverage if you need to learn the fundamentals.
PE funds are normally set up as Limited Partnerships between one General Partner (GP) and many Limited Partners (LPs).
The GP is the PE firm (i.e., the Partners with ownership stakes), and the LPs include institutional investors such as pension funds, funds of funds, and sovereign wealth funds.
The LPs and GP agree on terms such as the life of the fund (often around 10 years), the management fees, the distribution waterfall, and investment requirements such as company types, geography, and diversification.
The LPs contribute ~95%+ of the capital and, therefore, earn most of the investment profits if the fund is successful.
A PE firm typically operates several different PE funds at the same time, but all firms start with a single fund.
The fact that one individual at a PE firm could be involved with 1 or several PE funds at the same time creates some of the compensation uncertainty outlined above.
Components of Private Equity Compensation
At the junior levels in private equity, the main cash compensation components are your base salary and bonus.
Your base salary and bonus are both funded by the management fees the firm charges on its current funds.
For example, let’s say that your firm currently has a $1 billion fund it is actively investing, and it has $200 million of cost basis remaining on a previous $500 million fund.
In other words, it has already invested all $500 million of that fund and sold 60% of the companies, but $200 million of its investments remain unsold.
In this situation, the management fees might be based on 2% of the current active fund and 1% of the remaining cost basis in the older fund, so:
Total Fees = $1 billion * 2% + $200 million * 1% = $22 million.
Assuming your firm has no other active funds, everyone’s base salaries and bonuses will come from this $22 million pool.
There are sometimes other income sources, such as “monitoring and transaction fees” or “deal fees,” but the management fees account for most of the current income.
Beyond base salaries and bonuses, the other compensation components include carried interest, co-investments, and GP commitments, which all relate to the performance of specific funds.
What is Carry in Private Equity?
Carry, also known as carried interest, is a percentage of the investment profits that gets awarded to the PE professionals.
Carry is traditionally 20% of the investment profits, but it varies by firm size, strategy, and region.
Normally, the firm must clear a hurdle rate at the fund level or for individual deals to be eligible for this payout.
For example, if the hurdle rate is 8% and Carry is awarded at the fund level, the fund must earn an IRR of 8% on the total “Called Capital” (investments in portfolio companies + capital called for management fees) before any Carry distributions.
Many PE firms also let the professionals make co-investments by putting their own personal money into specific deals.
Unlike Carry, which is mostly available to VPs, Principals, and Partners/MDs, co-investments are often available to Associates as well.
Finally, there is the GP Commitment, which means the Partners of the firm are expected to contribute a percentage of each fund’s total capital, typically between 2% and 4%.
This GP Commitment effectively acts as a separate equity investment in the fund itself, so it can produce virtually any outcome.
Unlike the LPs’ Committed Capital, the GP Commitment does not earn Management Fees or Carry; it’s simply additional capital invested into the portfolio companies.
How Does Carry Work in Private Equity?
To illustrate how Carry and the GP Commitment work, I’ll use a simple example of a middle-market fund:
- Fund Size: $1 billion.
- GP Commitment: 2%.
- Management Fees: 2% of LP Committed Capital in the 5-year Investment Period and 1% of the Remaining Cost Basis in the post-Investment Period.
- Carried Interest: 20% with an 8% Hurdle Rate, accrued and compounded, calculated at the fund level.
- Investment Period: 5 years.
- Returns Profile:5x Gross Multiple of Invested Capital (MOIC) and an average realization time of 5 years (i.e., it takes 5 years to sell each portfolio company).
So, the GP must contribute $20 million, while the LPs contribute $980 million.
Of this $980 million, approximately $880 million will be invested in portfolio companies, and the remaining ~$100 million will pay for the Management Fees.
Management Fees continue after the 5-year investment period, so total Fees in real life will be closer to ~$115 million.
The cash-flow profile before Carry looks like this (larger version):
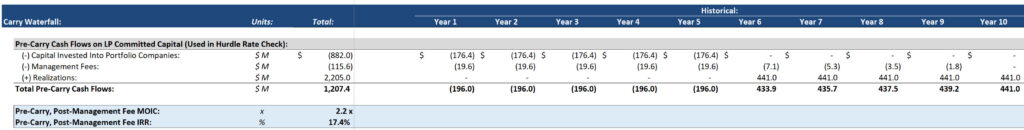
The 17% IRR here easily clears the 8% Hurdle Rate, so Carry will be distributed.
In the first step of the “Carry Waterfall,” the LPs earn back their Called Capital, which is close to $1 billion here.
This is easy because the Total Realization Proceeds from investments are $2.2 billion.
Then, they earn a “Preferred Return” based on 8% per year, compounded, which is distributed in Years 8 and 9 here:
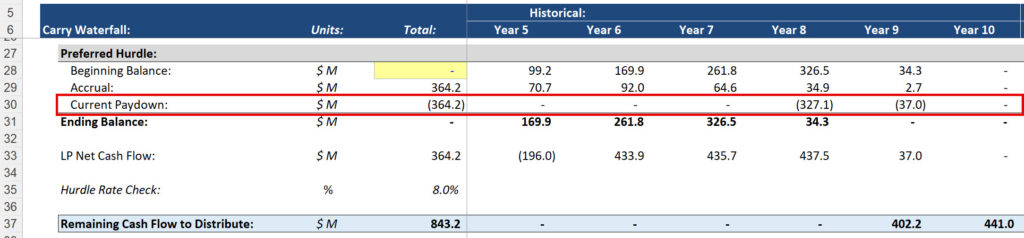
The GP is then “caught up” such that the Partners receive 20% of the total investment profits that correspond to this 8% IRR:
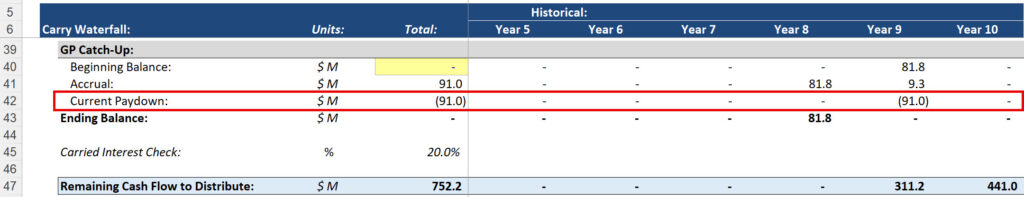
The LPs earn a Preferred Return of $364.2 million, so you divide by 80% to “gross it up” to 100%, and then distribute 20% to the GP:
$364.2 / 80% * 20% = $91 million, which is shown in the GP Catch-Up above.
The remaining cash flows after the Preferred Return and GP Catch-Up are now split 80% / 20% between the LPs and GP:
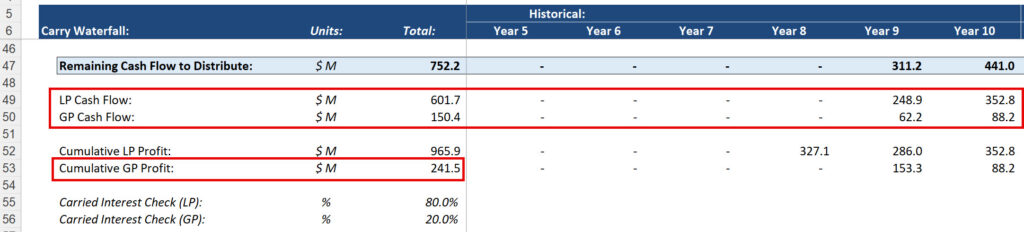
So, this fund produces $242 million of Carry over 10 years.
Amazing, right?
Well… not so fast.
Not all 100% of this Carry goes to the Partners because some is always set aside for non-Partner professionals and potential new/upcoming hires.
This percentage varies, but we’ll assume 30% for a fund of this size.
So, doing the math:
- Annualized Carry: $242 * 70% / 10 = $16.9 million.
There’s also the GP Commitment, which is a separate ~2% equity investment in the fund.
If you assume the LPs invest $176 million per year in portfolio companies, the GP must invest $176 / (1 – 2%) * 2% = $3.6 million per year in these same companies.
That’s a total of $18 million over the 5 investment years, so a 2.5x multiple results in exit proceeds of $45 million.
Therefore, the GP earns $27 million in net cash flows over these 10 years, or $2.7 million per year.
If this firm has 5 Partners, and each one earns $1 million per year in Base Salary + Bonus:
- Total Compensation per Partner per Year = $1 million Base/Bonus + $3.4 million Carry + $540K GP Commit = $4.9 million.
For a fund of this size, 5 Partners is about right at a new firm, but it’s on the low side for a mature/established firm.
With 10 Partners, it would be:
- Total Compensation per Partner per Year = $1 million Base/Bonus + $1.7 million Carry + $270K GP Commit = $3.0 million.
However, the Base Salary + Bonus would also be lower with 10 Partners, so I would put the annualized compensation in the “$2 to $3 million per year” range here.
Also, it’s highly unlikely that all 5 or 10 Partners get equal shares of the Carry; it could be something like 5% each for 7 Partners and ~22% for each of the other 3, for example.
Plus, this firm must have at least one other active fund if it can afford ongoing base salaries + bonuses in this range, which also changes the math.
Carried Interest in Middling and Poor Outcomes
To illustrate other outcomes, I’ll run through the math with two other scenarios:
- Scenario #1: The fund produces a 1.8x Gross MOIC (a mediocre outcome).
- Scenario #2: The fund produces a 1.4x Gross MOIC (a borderline disaster).
In Scenario #1, the fund just barely clears the Hurdle Rate (9.9% vs. 8.0%).
The Carried Interest is $118 million, or $83 million after payments to non-Partners:
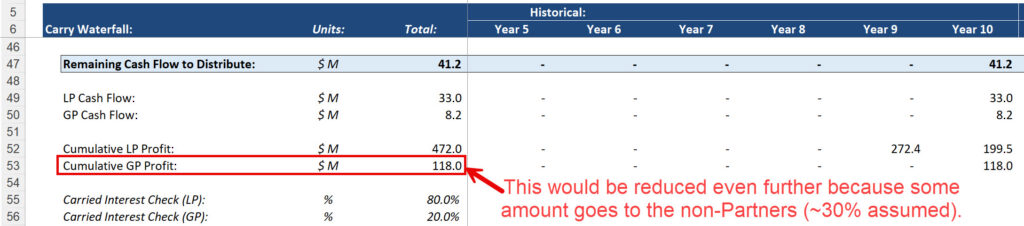
If we stick with 10 Partners and the same optimistic cash compensation:
- Scenario #1, Total Compensation per Partner per Year = $1 million Base/Bonus + $82K Carry + $144K GP Commit = $1.2 million.
It’s still a lot of money, but it’s far lower than the $2 – 3 million range above because the fund performance is much worse.
In Scenario #2, the fund does not clear the Hurdle Rate (4.4% vs. 8.0%):
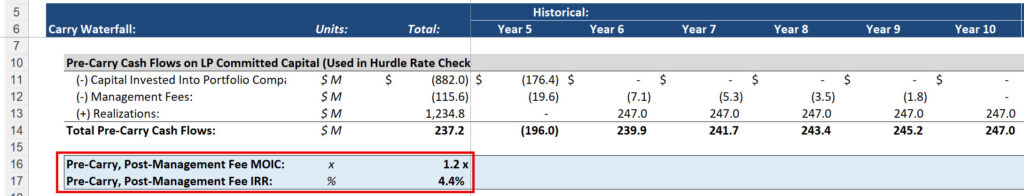
So, the Carried Interest is $0, and the Partners earn only their Base Salary + Bonus and the GP Commit.
The GP Commit adds a net amount of $7.2 million, so it’s an extra $72K per Partner per Year:
- Scenario #2, Total Compensation per Partner per Year = $1 million Base/Bonus + $0 Carry + $72K GP Commit = $1.1 million.
If a fund does well, Carry and the GP Commit could increase the Partner’s annualized compensation by 100%, 200%, or even 400%.
But if it does poorly, these components might just provide a modest boost.
So, What’s the Problem with Carry?
Carry can potentially make you very wealthy if you reach the Partner level and stay there as your funds perform well.
But it’s not a “sure thing” because of the following factors:
1) Performance – See above. It is not “easy” to earn a 2.5x Gross MOIC even for large/established firms.
For context, here are some real performance stats from TPG and Hamilton Lane over the past few decades (larger versions):
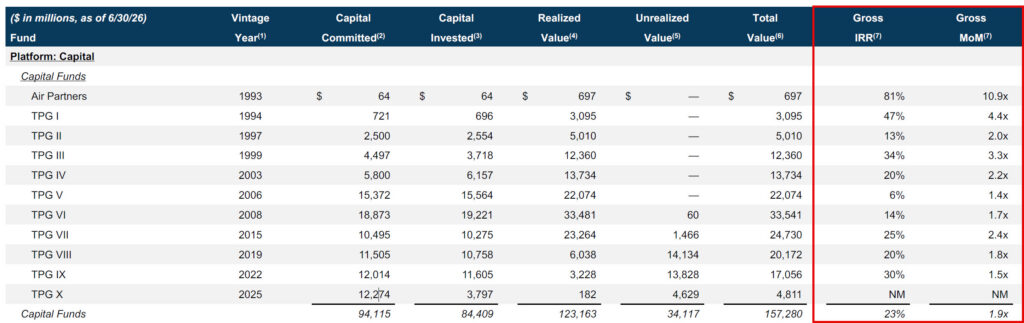
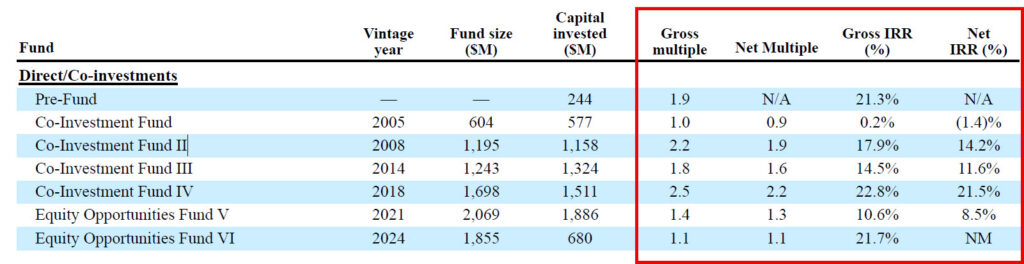
Also, even a seemingly small difference, such as a 2.5x vs. 2.0x multiple, can make a big impact on Carry because of the timing and the hurdle rate.
2) Carry Splits – I am simplifying above and assuming a simple split between all the “Partners.” But this varies based on seniority, office politics, founder vs. non-founder status, etc.
For reference, a standard VP at a middle-market fund like the one above might earn 0.25% to 1.00% of the Carry pool, a Principal might earn 1.0% to 2.0%, and a “normal” MD might earn 3.0% to 8.0% (with a “Managing Partner” potentially earning 10.0% to 20.0%).
3) “Annualized” is Misleading – Most of the Carry payout tends to come at the end of the fund’s life, so it’s very lumpy and sensitive to shifts in the last few exits.
4) Vesting Periods – It usually takes ~5 years for the full Carry percentage to vest, and if you leave or get forced out before that, you give up a portion of it.
5) Clawbacks – If Carry is awarded on a per-deal basis, but the entire fund underperforms, you may have to return some of the Carry to the LPs in a fun mechanism known as a “Clawback.”
6) Poor Exit Environment – Finally, many PE firms have been struggling to exit their portfolio companies, and performance stats for most post-2020 funds have been underwhelming.
If you join a larger firm, your base salary + bonus will be higher because of the larger fund sizes, but Carry could go either way.
Funds are bigger, so investment profit potential is higher, but performance is often worse, and it’s also harder to get promoted and win a meaningful percentage of the Carry pool.
Will Sky-High Private Equity Salaries, Bonuses, and Carry Last Forever?
The answer here depends on your definition of “forever.”
If you mean “for another 10 – 20 years,” sure, it could happen.
If you mean “for another 100 years,” I would be more skeptical.
If PE firms can keep raising new, larger funds, base salaries + bonuses should remain high and gradually increase over time.
So, if you join one of the mega-funds or an upper-middle-market firm, you probably have nothing to worry about.
It gets trickier with much smaller firms because there’s no guarantee they will continue to expand over time.
Carried Interest is an open question because of the poor exit environment and the fact that few Partners ever want to leave, despite being incredibly wealthy.
So, I would not base your entire career on the possibility of earning outsized Carry payments at the Partner level in PE.
Not only does it take 10-15+ years to reach this level, but you also need to stay there for a long time and work in funds with strong performance to truly benefit.
If we’re being honest, Carry mostly benefits people who got into the industry a long time ago, when it was much less competitive (both in terms of recruiting and investing successfully).
In the current environment, there are so many unknowns and risk factors that it’s dangerous to think of Partner-level PE compensation as a “sure thing.”
This doesn’t mean that you should avoid private equity.
It just means that you need to be realistic about what “sky-high compensation” really means, including all the fine print.
About the Author
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
Free Exclusive Report: 57-page guide with the action plan you need to break into investment banking - how to tell your story, network, craft a winning resume, and dominate your interviews
Comments
Read below or Add a comment
Hi Brian, your articles have been a great help when exploring various career options. One area I haven’t encountered much information about is working for a holding company. How can one get recruited? And what does career advancement typically involve in this field? Also, how does your day-to-day differ from private equity, given that you’re not focused on flipping these assets?
Thanks. Unfortunately, I don’t know much about holding companies and have never been able to find much on them. I will see if we can feature the topic in the future. My assumption would be that it’s a bit more like working for a traditional Limited Partner (LP) such as a pension fund or SWF, with a slower pace and lower compensation since you don’t “need” to make investments or exit them by certain dates. You probably take more time to evaluate assets and make long-term plans for them.